A rock chip can look minor at breakfast and become a windshield-length crack by the afternoon commute. Searches for “how to file windshield claim” information usually happen when drivers need answers quickly: Is the damage covered? Will there be a deductible? Can the glass be fixed today? The good news is that filing a claim is usually straightforward when you document the damage and know what to ask.
First, decide whether to repair or replace the windshield
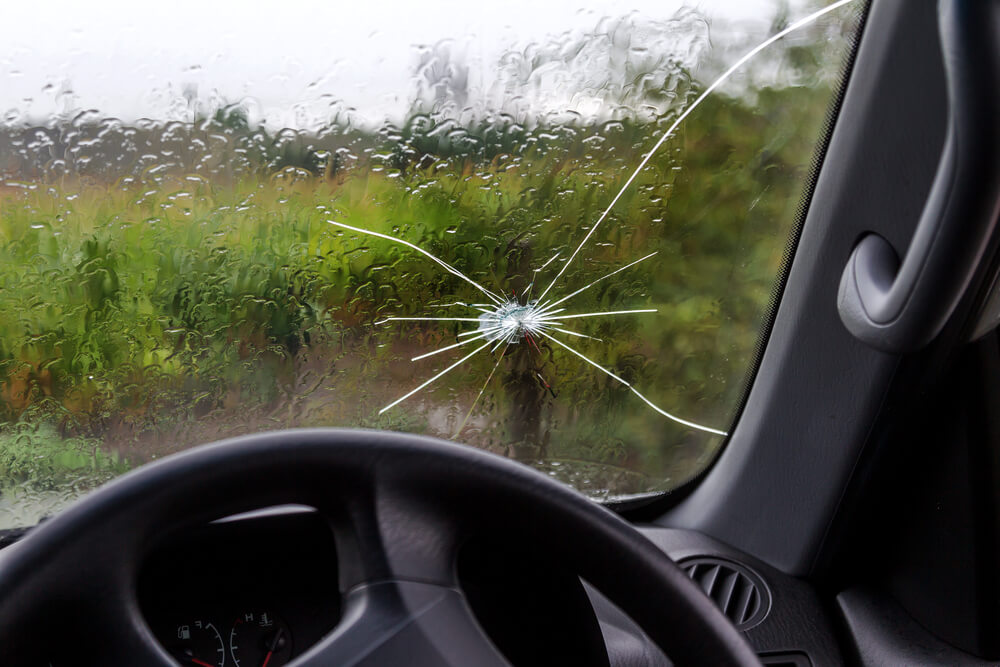
Before opening a claim, take a close look at the damage. A small chip or short crack may be repairable, especially when it is outside the driver’s direct line of sight. Repair is generally faster and costs less than a full windshield replacement. It can also help preserve the factory seal around the glass.
Replacement is more likely when the crack is long, spreading, deep, near the windshield edge, or directly in the driver’s viewing area. Damage near the edge can weaken the entire windshield, while damage in front of the driver can remain distracting even after a repair.
Do not wait too long to make the call. Heat, cold, rough roads, car washes, and even a slammed door can make existing damage spread. In North Texas, temperature swings and summer heat can turn a repairable chip into a replacement job faster than many drivers expect.
Check your auto insurance coverage before you file
Windshield damage is commonly handled under comprehensive coverage, not collision coverage. Comprehensive coverage generally applies to non-crash damage such as road debris, hail, vandalism, theft, and falling objects. However, every policy is different, so confirm the details with your insurer.
Look for your comprehensive deductible. If your deductible is $500 and the replacement cost is below or close to that amount, paying out of pocket may make more sense. On the other hand, some policies offer reduced or waived deductibles for windshield repair. A repair claim may be a practical choice when the insurer covers most or all of the cost.
Ask these questions when you call your insurance company:
- Does my policy include comprehensive auto glass coverage?
- What is my deductible for windshield repair or replacement?
- Is chip repair covered with no deductible?
- Does filing this claim affect my premium or claims history?
- Can I choose the auto glass company that performs the work?
The last question matters. Your insurer may recommend a glass network or preferred provider, but you can ask about using a local company that offers the scheduling and mobile service you need. If you drive for work, manage family schedules, or cannot leave a vehicle at a shop, mobile service can make a real difference.
How to file a windshield claim step by step
The best way to file a windshield claim is to have basic details ready before contacting your insurer. This keeps the conversation short and reduces the chance of a follow-up delay.
1. Take clear photos of the damage
Photograph the chip or crack from inside and outside the vehicle if possible. Take one close image that shows the damage clearly and another that shows its location on the windshield. If a rock or other debris caused the damage and it is safe to photograph, include that as well.
Photos help establish the condition of the glass before repair or replacement. They can also be useful if a crack spreads before your appointment.
2. Gather your policy and vehicle details
Have your insurance card or policy number available, along with the vehicle identification number, license plate number, year, make, model, and current mileage. The insurer may also ask when and where the damage occurred.
You do not need a perfect explanation. Be accurate and simple. For example: “A truck kicked up a rock on the highway this morning, and it chipped the windshield.” Avoid guessing at details you do not know.
3. Contact your insurer or start the claim online
Most major insurers let customers begin a glass claim by phone, through an app, or online. Tell the representative that you have windshield damage and want to confirm whether repair or replacement is covered.
During the claim, write down the claim number, the representative’s name, your deductible amount, and any instructions about billing or inspection. If the insurer authorizes a glass company directly, ask whether the company can verify the claim and collect only your deductible at the time of service.
4. Schedule the glass service promptly
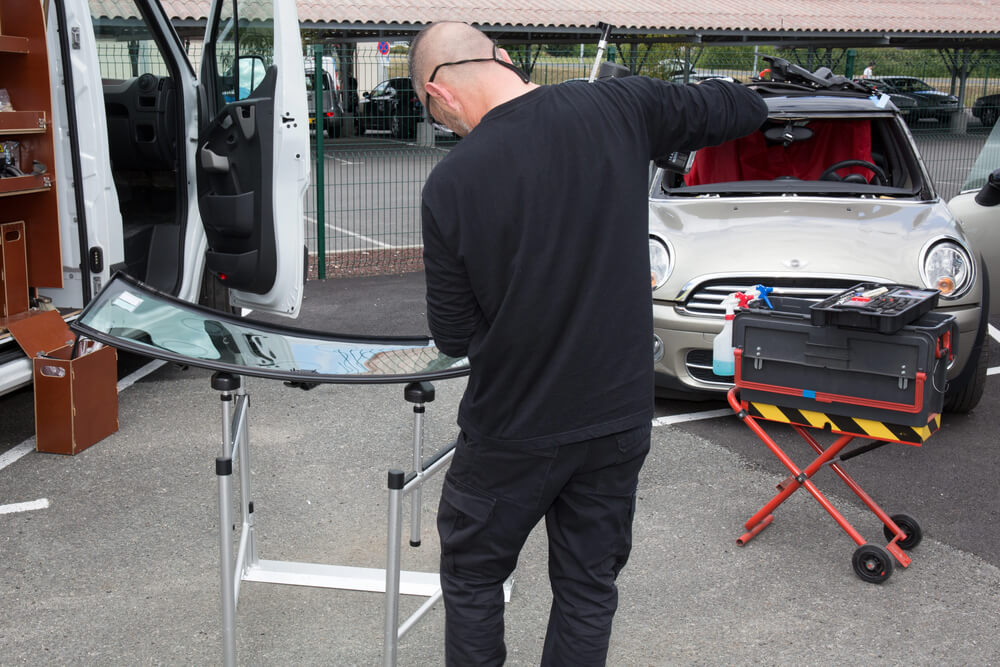
Once the claim is started, schedule repair or replacement as soon as you can. A mobile auto glass technician can often come to your home, office, or another safe location, so you do not have to spend time in a waiting room or rearrange your entire day.
For drivers in Dallas, Addison, Richardson, Irving, or Fort Worth, that can mean getting the windshield handled while you work, manage school pickup, or stay at home. The vehicle must be parked safely and have enough room around it for the technician to work.
5. Confirm what you will pay
Before the appointment, confirm whether you owe a deductible, whether the insurer pays the glass company directly, and whether any additional work is needed. A proper replacement may require recalibration of advanced driver-assistance features, such as cameras behind the windshield used for lane departure warnings, automatic emergency braking, or adaptive cruise control.
Recalibration is not optional when your vehicle requires it. Ask whether it is included in the estimate or claim authorization. Skipping it can leave safety features inaccurate, even if the new windshield looks perfect.
What not to do after windshield damage
Do not cover a chip with tape unless it is a temporary measure to keep dirt and moisture out. Avoid power washing the windshield, parking in extreme direct sun when possible, and blasting the defroster onto a cold damaged windshield. Each of these can encourage the crack to grow.
It is also smart not to authorize a replacement before you understand your deductible and coverage. Emergency situations are different, of course. If the windshield is severely shattered, blocks your view, or creates an unsafe driving condition, prioritize safety and arrange service immediately.
Finally, do not assume every crack can be repaired. A quick repair may sound less expensive, but trying to repair damage that is too large or poorly located can leave you with compromised visibility and still require a replacement later.
Repair claims versus replacement claims
A repair claim is often simpler because it involves less labor, fewer parts, and a lower cost. The technician injects specialized resin into the damaged area, cures it, and polishes the surface. The repair can reduce the appearance of the chip and help prevent it from spreading, although it may not disappear completely.
A replacement claim involves removing the damaged windshield, preparing the frame, installing new glass with the proper adhesive, and allowing the adhesive to cure according to safe drive-away requirements. Depending on the vehicle, it may also involve molding replacement and camera recalibration.
Neither option is automatically better. Repair is preferable when the damage qualifies and visibility will not be affected. Replacement is the safer choice when the windshield’s structural strength or your line of sight is at risk.
Keep your claim paperwork until the job is complete
Save the claim number, estimate, invoice, payment receipt, and any recalibration documentation. Check the completed work before leaving or before the mobile technician departs. The glass should be clean, securely installed, and free of obvious gaps or loose trim. If a camera recalibration was required, ask for confirmation that it was completed.
A windshield claim should not add another week of stress to an already busy schedule. Start with clear photos, verify your coverage, and choose service that fits where you are. Mid Cities Auto Glass can help DFW drivers move from damaged glass to a safer view of the road without making a shop visit the hardest part of the day.